Eu Moves To Integrate European Capital Markets To Unlock Billions In Business Investment
EU Capital Markets Reform: What It Means for European Businesses
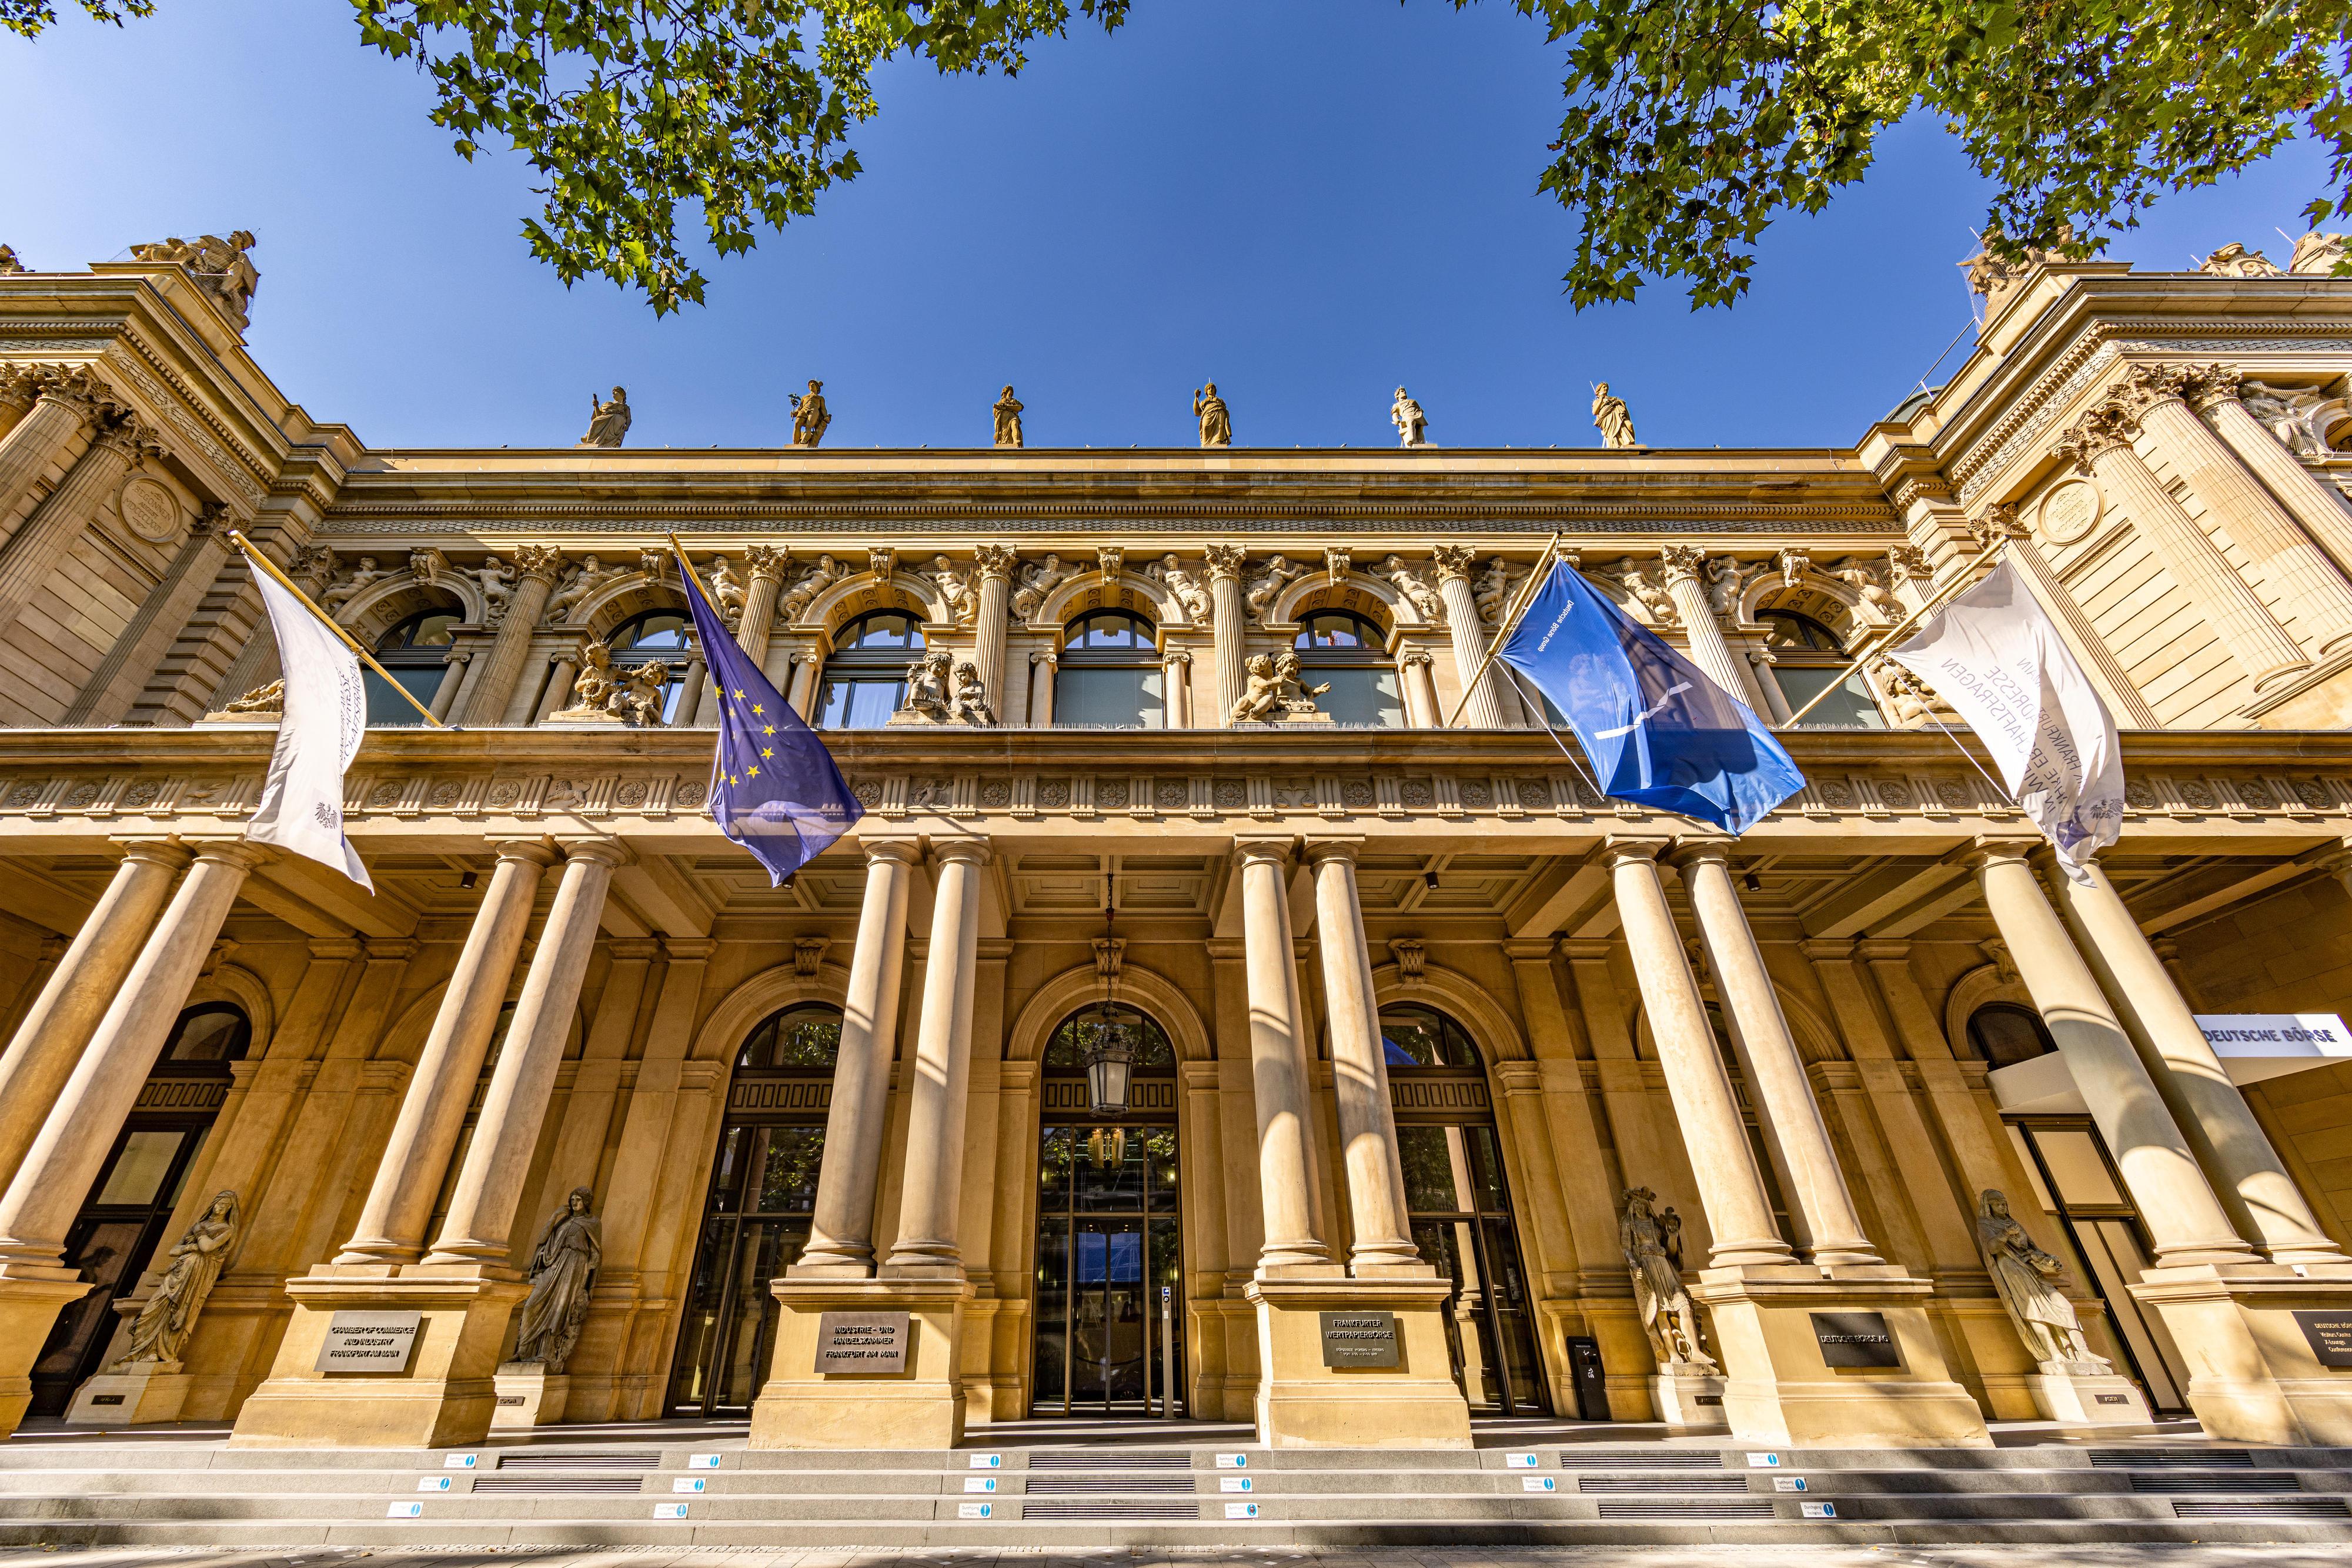
The European Union has taken a significant step towards integrating its fragmented financial markets, aiming to make it easier for businesses to raise capital, improve investment opportunities for citizens and strengthen Europe's competitiveness against major economies such as the United States.
On 9 October 2026, EU finance ministers reached an agreement on the main elements of their negotiating position for the Market Integration and Supervision Package (MISP). The proposed reforms would strengthen the role of the European Securities and Markets Authority (ESMA), reduce barriers for financial firms operating across national borders and improve the way investment capital moves throughout the European Union.
The initiative forms part of the EU's broader Savings and Investments Union strategy, which aims to connect household savings with businesses that need funding to expand, innovate and create jobs.
According to the Council of the European Union, approximately €10 trillion in household savings is currently held in bank deposits across the bloc. EU policymakers want to make it easier for some of this capital to flow into productive investments, although participation would depend on individual choices, market conditions and the risks associated with financial products.
The latest agreement represents progress towards that goal, but it is not yet a final law. Negotiations with the European Parliament are still required before the package can be adopted. [Source: Council of the European Union, 9 October 2026.]
Why Does Europe Want to Integrate Its Capital Markets?
Europe has a large economy, substantial household savings and many innovative businesses. However, its financial markets remain divided by national rules, supervisory practices and legal differences.
A company seeking investment across several EU countries can face different regulatory requirements, reporting procedures and market structures. These differences can increase administrative costs and make cross-border expansion more complicated.
The problem is particularly relevant for businesses looking to grow beyond their home markets. A startup may develop a promising product in one European country but struggle to access investors, institutional funding or public markets in other member states.
In a more integrated financial system, investors could find it easier to access opportunities across the EU, while companies could potentially reach a larger pool of capital without navigating as many national barriers.
The European Commission has argued that stronger capital markets are important for funding innovation, clean technology, artificial intelligence, biotechnology and other strategic industries.
Its Savings and Investments Union strategy is designed to improve the connection between savings and productive investment, giving businesses more financing options and citizens more opportunities to make financial decisions suited to their circumstances.
However, integration alone cannot guarantee more investment. Companies must still demonstrate commercial potential, investors must assess risk, and the EU needs effective supervision to maintain confidence in its financial system.
What Is the Market Integration and Supervision Package?
The Market Integration and Supervision Package is a set of proposed legislative measures intended to improve how European financial markets operate across borders.
The package includes three legislative proposals covering regulation, directives and settlement finality. Its main objectives include more consistent supervision of major market operators, fewer barriers for cross-border financial businesses and improved conditions for investment.
One of its most important elements is the proposed expansion of ESMA's direct supervisory responsibilities.
Currently, many financial market operators are supervised by national authorities. While EU-wide rules already exist in several areas, differences in implementation and oversight can create complexity for businesses operating in multiple countries.
Under the Council's agreed negotiating position, ESMA would directly supervise the most significant cross-border trading venues and important post-trading entities, including certain central counterparties and central securities depositories.
These organisations play essential roles in financial markets. Trading venues bring buyers and sellers together, central counterparties help manage risks between parties to financial transactions, and central securities depositories support the safekeeping and settlement of securities.
More consistent oversight could reduce some regulatory differences and improve confidence in cross-border financial activity.
The Council's version of the proposal is narrower than the European Commission's original plan in several respects. The final outcome will depend on the negotiations that follow.
[Source: Council of the European Union, Market Integration and Supervision Package, October 2026.]
How Could the Reforms Help European Startups and SMEs?
For startups and small and medium-sized enterprises (SMEs), access to funding can determine how quickly a business develops new products, hires employees or enters new markets.
Bank loans remain important, but companies may also seek venture capital, private investment, bonds or eventual access to public stock markets.
A more integrated European capital market could help businesses connect with investors outside their home countries.
1. Access to a broader investor base
A company based in Spain, France, Germany or another EU member state may benefit from a financial system in which investors can evaluate opportunities across borders more easily.
Greater integration could improve the visibility of businesses seeking investment and create more opportunities for cross-border financing.
This may be particularly valuable for companies in capital-intensive sectors, including technology, healthcare, advanced manufacturing and clean energy.
Nevertheless, a larger potential investor pool does not guarantee funding. Investors will continue to consider a company's revenue, growth prospects, financial controls and competitive position.
2. Lower administrative barriers
Businesses operating across multiple European markets may need to work with different financial institutions and navigate varying national procedures.
Reducing unnecessary regulatory complexity could lower some costs for financial firms and make it easier for them to offer services across the EU.
For startups, this could eventually mean improved access to investment services and a wider choice of financing partners.
The immediate impact will depend on the final legislation, how it is implemented and whether the resulting changes genuinely reduce costs for smaller businesses.
3. More opportunities to scale
A startup that succeeds in its home market may need substantial additional capital to expand across Europe.
More integrated capital markets could help investors identify opportunities in different countries and support companies seeking larger funding rounds.
Over time, policymakers hope this will help more European companies grow into major international businesses rather than moving their headquarters or primary fundraising activity to other markets.
However, financial integration is only one part of the solution. Differences in taxation, insolvency law, business regulation and local market conditions can still affect cross-border growth.
What Does the Plan Mean for European Investors and Savers?
The EU's strategy is not only about helping businesses obtain funding. It also aims to give citizens more opportunities to invest their savings.
The Council estimates that approximately €10 trillion in household savings is held in low-yield bank deposits across the EU. Policymakers believe a more integrated capital market could offer savers greater access to investment opportunities while helping businesses obtain capital.
For example, a household that chooses to invest may be able to access a wider range of funds, shares or other regulated financial products through financial institutions operating across borders.
However, investment is not the same as holding money in a bank deposit. Investments can lose value, returns are not guaranteed, and products differ in liquidity, fees and risk.
The objective should not be to encourage every saver to move money out of deposits. Households need access to cash for emergencies and short-term expenses, and the appropriate balance between saving and investing depends on individual circumstances.
Instead, the EU wants to improve the financial infrastructure and market access that allow citizens to make informed choices.
For the strategy to succeed, consumer protection, clear information and reliable financial supervision will remain essential.
ESMA's Role Could Become More Important
The proposed reforms would give ESMA, based in Paris, a greater role in supervising important financial market operators with significant cross-border activities.
Supporters argue that more consistent supervision could help reduce differences in how EU financial rules are applied. A common supervisory approach may also make it easier for financial firms to operate in multiple member states.
The Council's position would establish a new full-time ESMA executive board, consisting of a chair and five independent full-time members. The board would manage operations and make decisions concerning entities directly supervised by ESMA.
National authorities would retain important responsibilities. The Council's approach preserves a separate board of supervisors as ESMA's principal body for regulatory decisions, strategy, budget and supervisory convergence.
The package also envisages a transition period during which European and national experts would work together to transfer supervisory responsibilities.
These arrangements reflect an attempt to balance stronger EU-level supervision with continued national involvement.
The negotiations will determine how these powers are ultimately allocated and how the new framework will operate in practice.
Digital Assets and Financial Technology Are Also Part of the Plan
The reforms address technological developments that are changing how financial assets are traded and settled.
The Council's negotiating position would improve the existing distributed ledger technology pilot regime, a controlled framework that allows eligible market participants to test certain uses of distributed ledger technology in financial markets.
Distributed ledger technology can support digital representations of financial assets and potentially streamline some trading and settlement processes.
For example, tokenisation can represent ownership or rights associated with financial assets in digital form. Depending on the structure, it may offer opportunities to improve transaction processing, record-keeping and access to financial infrastructure.
However, digital assets introduce their own challenges, including operational resilience, cybersecurity, legal certainty and the management of financial risks.
The Council's position also takes a more targeted approach to direct ESMA supervision of crypto-asset service providers, focusing initially on the most significant cross-border firms rather than automatically applying the same arrangement to every provider.
The final rules will determine how the new framework affects financial technology companies and market participants.
Challenges That Could Limit the Impact
Despite the potential benefits, building a more integrated European capital market will take time.
National interests may slow implementation
EU member states have different financial systems, market structures and policy priorities. Negotiations over supervisory powers demonstrate that governments do not necessarily agree on how far authority should move from national regulators to EU institutions.
The Council's agreement is a compromise, and further discussions with the European Parliament could change the final framework.
Better rules cannot eliminate investment risk
Even if cross-border investment becomes easier, companies must still compete for funding. Businesses with weak financial performance may struggle to attract capital, while investors will remain exposed to market fluctuations and possible losses.
Other barriers will remain
Tax systems, insolvency procedures, business laws and differences in national markets can still complicate investment across Europe.
Capital-market reforms may improve access to finance, but they cannot replace broader economic reforms or guarantee that companies will invest the money they raise productively.
What Happens Next?
The next stage is the legislative negotiation process between the Council of the European Union and the European Parliament.
The Council agreed on the main elements of its negotiating position on 9 October 2026. Formal adoption and negotiations on the final package remain necessary before the measures can become law.
Businesses, financial institutions and investors should therefore treat the agreement as an important policy development rather than an immediate change to every aspect of Europe's financial system.
The practical effects will depend on the final legislation, implementation timetable and the extent to which the reforms reduce barriers to cross-border financial activity.
Conclusion: Europe Seeks a More Competitive Financial System
The EU's latest move to integrate its capital markets reflects a broader ambition to strengthen Europe's economic competitiveness and make better use of its financial resources.
By reducing fragmentation, improving supervision and making cross-border investment easier, policymakers hope to connect European savings with companies that need capital to innovate and expand.
For startups and SMEs, the reforms could eventually create more opportunities to approach investors across the bloc. For savers, they could improve access to investment choices, while financial institutions may benefit from a more consistent framework for operating across national markets.
The agreement is an important step, but not the end of the process. The final legislation and its implementation will determine whether the reforms translate into lower barriers, broader access to capital and stronger growth for European businesses.
Disclaimer: This article is for general news and informational purposes only. It does not constitute financial or investment advice.